
23 March, 2020
Kai Kong Chay, Greater China Specialist
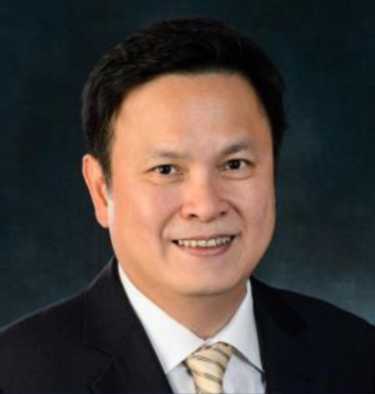
The ongoing coronavirus (COVID-19) outbreak, coupled with recent oil-price volatility, have placed pressure on Hong Kong and China equities. In this investment note, Kai Kong Chay, Greater China Specialist, provides an update on the asset class and explains why he thinks that corporates will weather the uncertain backdrop and still deliver positive earnings growth in 2020.
Despite the coronavirus outbreak and the oil-price slump, offshore Hong Kong and China equities have been resilient, with the MSCI China Index outperforming the MSCI World Index by over 12 percentage points. Furthermore, the Shenzhen Stock Exchange Composite Index is one of the world’s most resilient indices this year1 . In this investment note, we will share our views on some of the investment themes that have been affected by the recent uncertainty, such as consumption, and provide an update on our secular long-term themes.
In an early effort to contain the virus, the Chinese government extended the Lunar New Year holiday, introduced quarantine measures and imposed traffic restrictions. As a result, factory production and new orders in the country collapsed to record lows in February2 . Therefore, it will not be a surprise if the first-quarter earnings of China’s corporates are negatively affected. It is now mid-March, and we can already see a gradual and orderly resumption of industrial production in 90%3 of the country’s provinces (excluding Hubei). Also, the government’s supportive policies, such as lowering benchmark lending rates, suspending corporates’ social security payments, and the potential for further fiscal stimulus with new infrastructure projects, mean that the impact of COVID-19 on China’s economy should be relatively limited this year.
As the COVID-19 outbreak has now extended globally, earnings forecasts for Chinese equities have declined to 8%.4 Nevertheless, investors shall continue to see investment opportunities in companies that have the potential to deliver solid earnings growth over the next two-to-three years.
Seasoned investors have taken the sell-off opportunities to reinforce high conviction ideas and avoid names with more downside risks. Considering the global outbreak of COVID-19, investors should fine-tune their focus within consumption sector— cautious in travel and tourism related names and positive on domestic-driven consumption services. We believe there may be more negative surprises from travel-related sectors in the first quarter and the first half of this year, as restrictions on movement are now being extended globally and are should remain in place for the next few months.
The recent commodity-market tumble has fanned the flames of an already volatile stock market. US Brent crude oil collapsed by as much as 34% on 9 March5 , after Saudi Arabia shocked the market by launching a price war against Russia.
We believe investors should maintain defensive approach to the energy sector6 :
Despite this uncertain backdrop, the key secular trends that form the basis of our three investment themes remain unchanged:
The COVID-19 outbreak is undoubtedly causing a great deal of uncertainty among investors that is translating into heightened market volatility. However, by remaining calm and looking through the near-term disruption, we can see that current events may not necessarily act as a drag on China’s economic and earnings growth. As such, investors should focus on the longer-term investment themes that are designed to provide stable and secular growth.
1 Bloomberg, as of 16 March 2020. Year-to-date index price returns in local currency: MSCI China Index: -15.11%; MSCI World Index: -27.80%; Shenzhen Stock Exchange Composite index: -0.63%.
2 Caixin/Markit Manufacturing Purchasing Managers’ Index, February 2020.
3 HKEJ, 17 March 2020
4 Bloomberg, 17 March 2020. China equities refer to MSCI China.
5 Bloomberg, 10 March 2020.
6 Manulife Investment Management, 10 March 2020.
7 Estimate compound annual growth rate (CAGR) from 2018 to 2023. CNInsights, China Property Management Association, January 2019.
Fed hikes rates for first time since 2023 as expected
Today’s Federal Open Market Committee (FOMC) decision and press conference went smoothly—a welcome development, in our judgment, after the mixed signals that emerged from the Fed’s July meeting. The rate decision: A 25 basis-point (bps) hike, bringing the federal funds rate from 3.75% to 4.00%.
Beyond AI hype: How Manulife Global Multi Asset Diversified Income Fund (GMADI) evaluates long-term equity opportunities
AI continues to create potential investment opportunities, but we believe not every AI-related company will become a long-term winner. Rather than maximising exposure to the theme, the Manulife Global Fund - Global Multi-Asset Diversified Income Fund takes a selective and valuation-aware approach. In this investment note, we discuss the three characteristics we look for when identifying long-term winners and how these principles are reflected in the Fund's equity sleeve which currently maintains a constructive view on sectors such as communication services, healthcare, consumer staples and energy. This positioning reflects our bottom-up conviction in individual businesses whose long-term fundamentals, cash flow characteristics and valuations are viewed favourably by the investment team.
Asia High Yield has reached new highs; what’s next?
Asia High Yield (HY) bonds, known for providing an attractive source of income, present a very different opportunity set today compared to the pre-pandemic era. As discussed in our investment note from nearly a year ago, the asset class is no longer dominated by Chinese Mainland property developers. Instead, it has become more diversified, with investment opportunities spanning multiple areas, such as financial institutions, gaming operators, infrastructure providers, and selected frontier markets.
Fed hikes rates for first time since 2023 as expected
Today’s Federal Open Market Committee (FOMC) decision and press conference went smoothly—a welcome development, in our judgment, after the mixed signals that emerged from the Fed’s July meeting. The rate decision: A 25 basis-point (bps) hike, bringing the federal funds rate from 3.75% to 4.00%.
Beyond AI hype: How Manulife Global Multi Asset Diversified Income Fund (GMADI) evaluates long-term equity opportunities
AI continues to create potential investment opportunities, but we believe not every AI-related company will become a long-term winner. Rather than maximising exposure to the theme, the Manulife Global Fund - Global Multi-Asset Diversified Income Fund takes a selective and valuation-aware approach. In this investment note, we discuss the three characteristics we look for when identifying long-term winners and how these principles are reflected in the Fund's equity sleeve which currently maintains a constructive view on sectors such as communication services, healthcare, consumer staples and energy. This positioning reflects our bottom-up conviction in individual businesses whose long-term fundamentals, cash flow characteristics and valuations are viewed favourably by the investment team.
Asia High Yield has reached new highs; what’s next?
Asia High Yield (HY) bonds, known for providing an attractive source of income, present a very different opportunity set today compared to the pre-pandemic era. As discussed in our investment note from nearly a year ago, the asset class is no longer dominated by Chinese Mainland property developers. Instead, it has become more diversified, with investment opportunities spanning multiple areas, such as financial institutions, gaming operators, infrastructure providers, and selected frontier markets.
©1999 - 2026 Manulife Investment Management (Hong Kong) Limited


